LC Ideas: Views & Insights
Equity Insights: There are decades where nothing happens; and there are weeks where decades happen
Drishtant Chakraberty Senior Associate, Investment Consulting, Lighthouse Canton
Table of Contents
Up 23% + in the last 8 days the Hang Seng Index has returned almost all of what it managed to over the past 10 years (31.4%).The combination of fiscal and monetary policy announced by China last week has provided a much-needed boost to the Chinese equity markets, which have underperformed other global indices by a significant extent over the last 10-years.
Will this rally in Chinese securities continue?
The structural issues (highly leveraged balance sheets; youth unemployment etc.) that have plagued the Chinese economy won’t be solved overnight, but what has been seen time and again is that equity markets tend to be forward looking and move 6-9 months ahead of the underlying fundamentals. Based on this, we believe that the recent momentum, positive flow into the Chinese markets should not be ignored and provide an opportunity to build up positions in high quality bottom-up opportunities, which continue to trade at dirt-cheap valuations even after the sharp move seen over the past 2-weeks.
How to position?
Index / broad market ETFs tend to have all category of businesses, and the lower rung businesses (from a quality perspective) tend to be first when it comes to profit taking and stalling out after a large broad-based move in the indexes and hence such ETFs tend to deliver diffused performance. However, we believe that these can be a viable alternative for investors looking to gain exposure to a revival in broad based investor sentiment surrounding Chinese equities.
We’re also bullish on the following themes where we see the highest chance of sustained earnings growth and re-rating of valuation multiples which have not differed by much, based on quality (as they usually/must do) across Chinese stocks during this period of sluggish growth and policy uncertainty :-
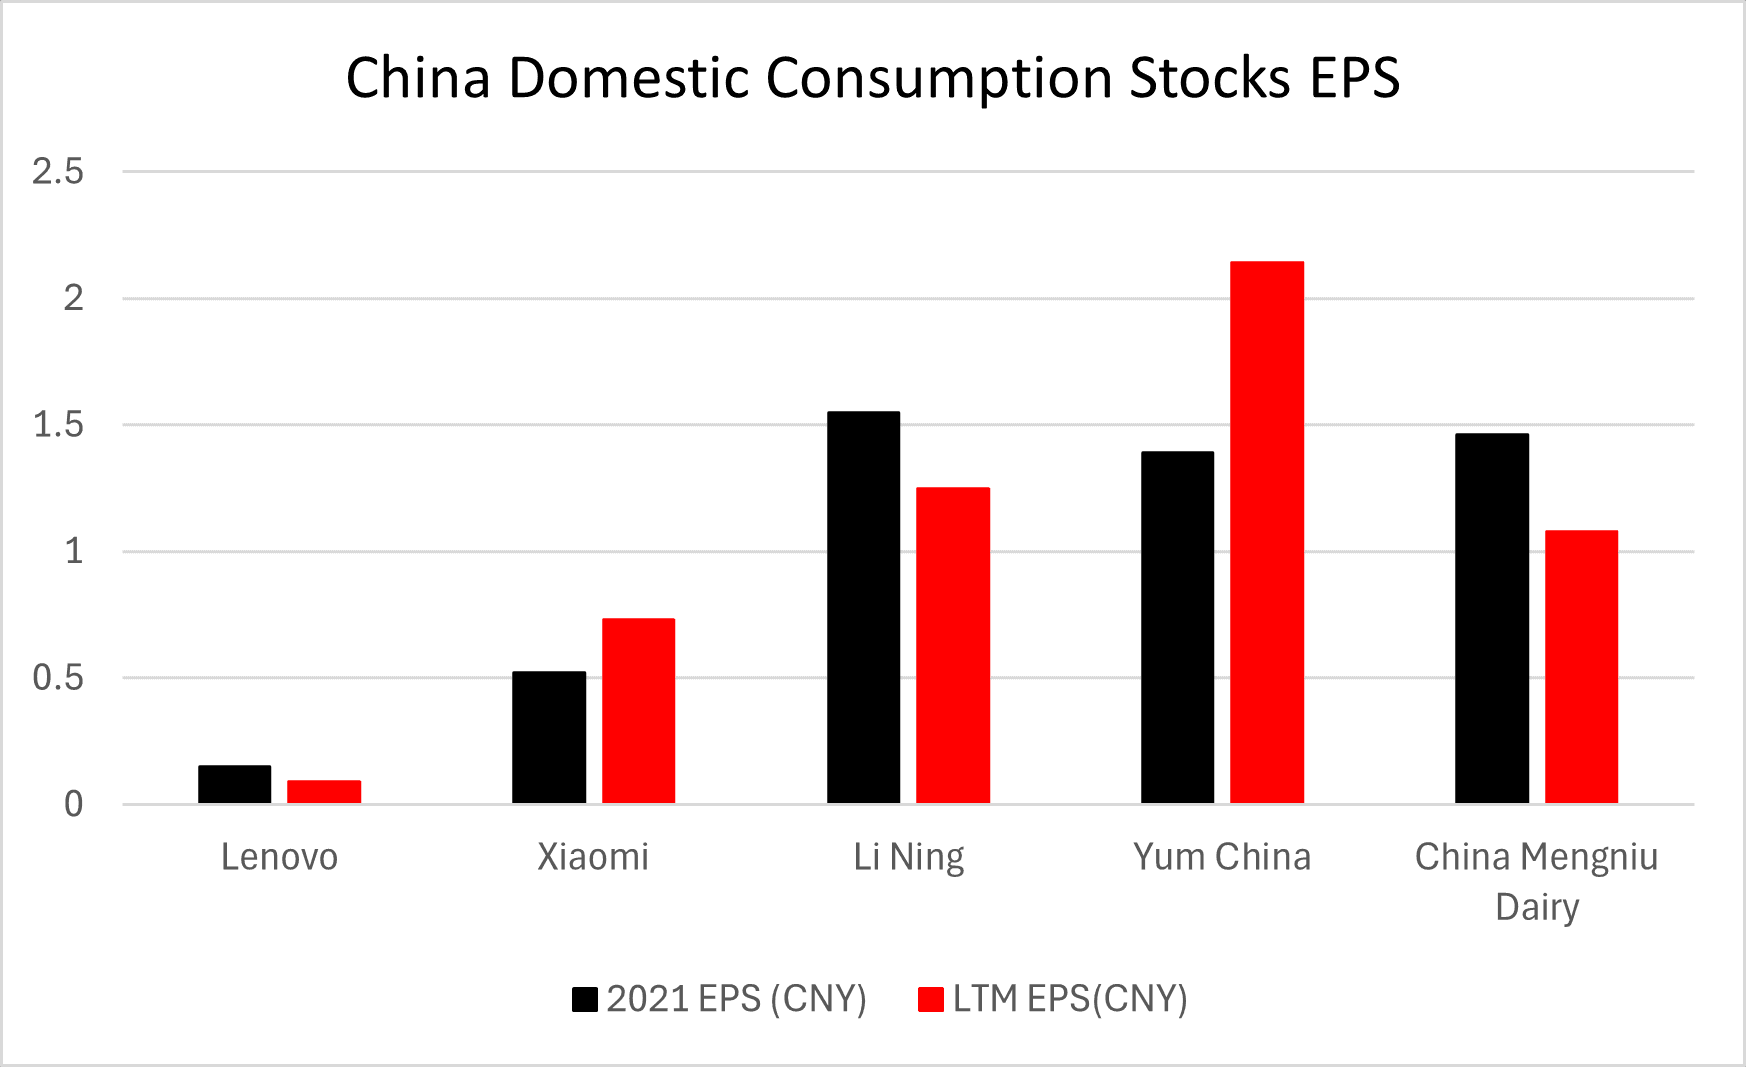
Numerous Chinese businesses that depend on domestic consumption have faced a particularly tough time (and many have failed to) in firstly keeping their topline steady and secondly, doing so while maintaining their margins. This has caused many such businesses to post earnings de-growth over the past few years, which are likely to get reversed in case of the stimulus package delivering on what it is supposed to.
Chinese automobile businesses
have taken over the world’s production of cars over the past few years and we believe that their domination is set to increase over the coming decade as once again when it comes to manufacturing, no one seems to be able to match China on pricing. Additionally, we would also like to note that the Teslas of the world are not too far ahead when it comes to the technological aspect of modern-day cars (ADAS, battery technology, car efficiency and performance). Further, we feel that the European automobile manufacturing business is pretty much broken, given that it just does not work without the cheap energy that they used to source from Russia. Just in the last week we have seen Stellantis miss its numbers; Volkswagen issue its second profit warning in 3-months and Aston Martin issue a profit warning as well. Much of this loss of market share that the European auto-manufacturers are facing is due to Chinese companies selling cars that are much cheaper and arguably of a higher quality. While the sanctions placed by EU definitely have an impact, we doubt whether they’ll be able to defend the interests of the domestic manufacturers which have fallen off quite significantly on the quality and pricing front.
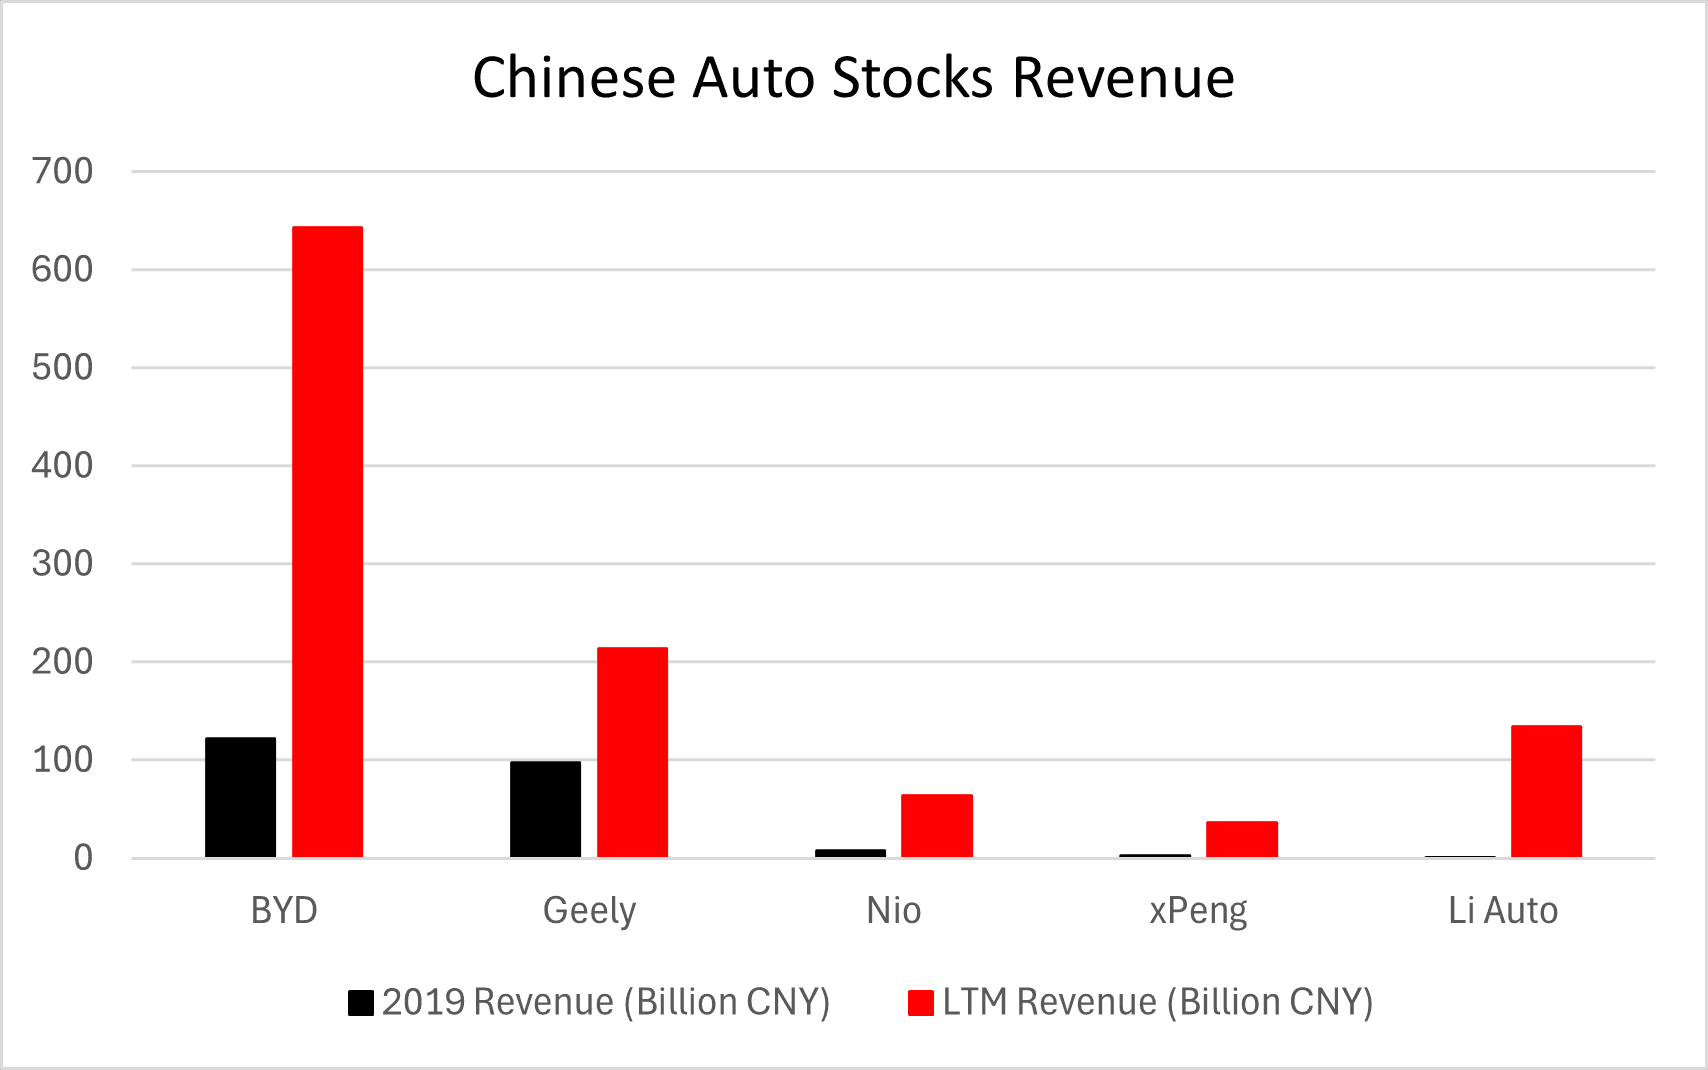
Most of the larger players in the Chinese automobile industry have managed to grow their businesses by a significant extent, which is evident from the large spike seen in their revenues over the past 5-years.
All investments carry risk, for more important information please read this disclaimer.


