Investment Insights
Fixed Income Insights: Finding Value in Bonds- A Relative Value Series (Part II)
Joydeb Chatterjee, CFA Executive Director - Investment Advisory and Fixed Income Selections, Lighthouse Canton
Table of Contents
Averages hide more than they reveal, and in case of aggregated credit spreads on bonds (near record lows), misses the relative value at the sector level within the asset class.
Using Option Adjusted Spreads (OAS - excess yield offered by a bond over the relevant maturity risk free rate, adjusted for embedded options), our trend analysis focuses on OAS at the sector level, relative to their own history, thereby eliminating the bias in spread variation caused by duration differences.
This is a two part series analysis. You can read part I of the analysis here: Fixed Income Insights: Finding Value in Bonds- A Relative Value Series
In this series we aim to analyze and surface such relative value opportunities across US Investment Grade, US High Yield and US EM bonds:
Chapter 2 - US High Yield Relative Value
Chapter 3 - US Emerging Markets Relative Value
Chapter 2- US HY Relative Value
We scanned through the 11 sectors that makeup the universe and concluded that Communication sector offers the highest relative value. This is most likely owing to the capex intensive nature of the industry resulting in higher net leverage. Highest number of distressed securities are also a probable cause behind such levels of spreads.
Interestingly, we also observed the following similarities in spread movements in 9 of them, with the exception being Healthcare and Financials.
Pre-pandemic peak was between Feb/ Mar 2016
Pandemic peak was in March 2020
Majority of the sectors except for Communications are trading precariously close to their all-time lows. Such massive spread compression has happened on paucity of new issues in the market which is extremely dangerous as issuers come to the market now to meet their refinancing needs.
Basis the above measure, Communication in our opinion offer the best relative value in the HY universe (see rebased chart).
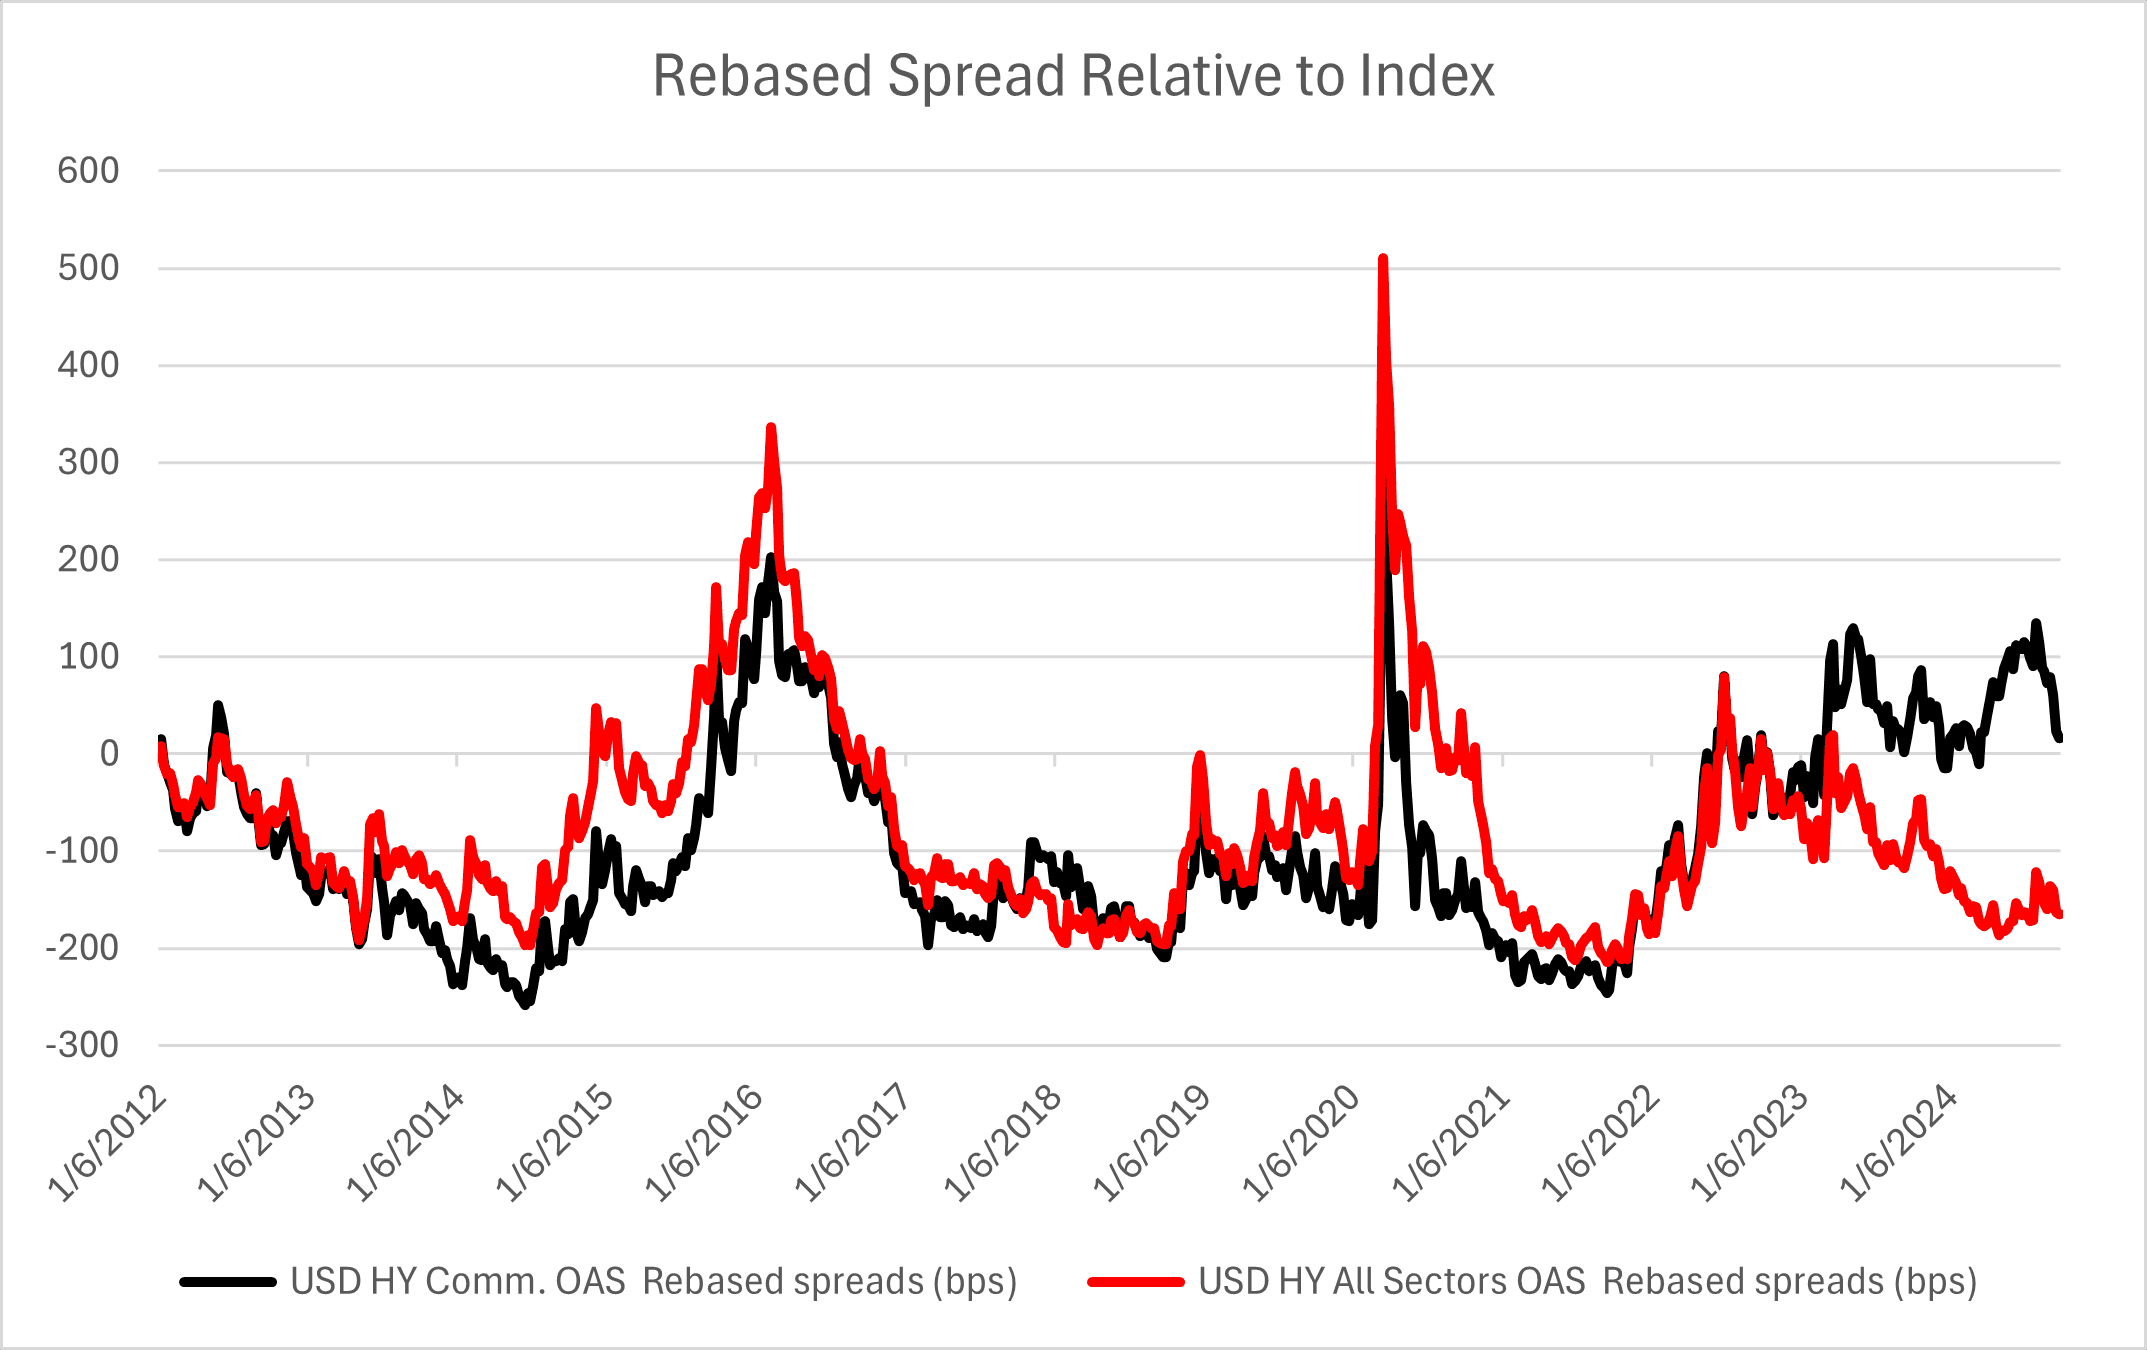
The above depicts the extent of relative value each sector offers relative to the index in general. It depicts the differential spreads variance relative to the start date.
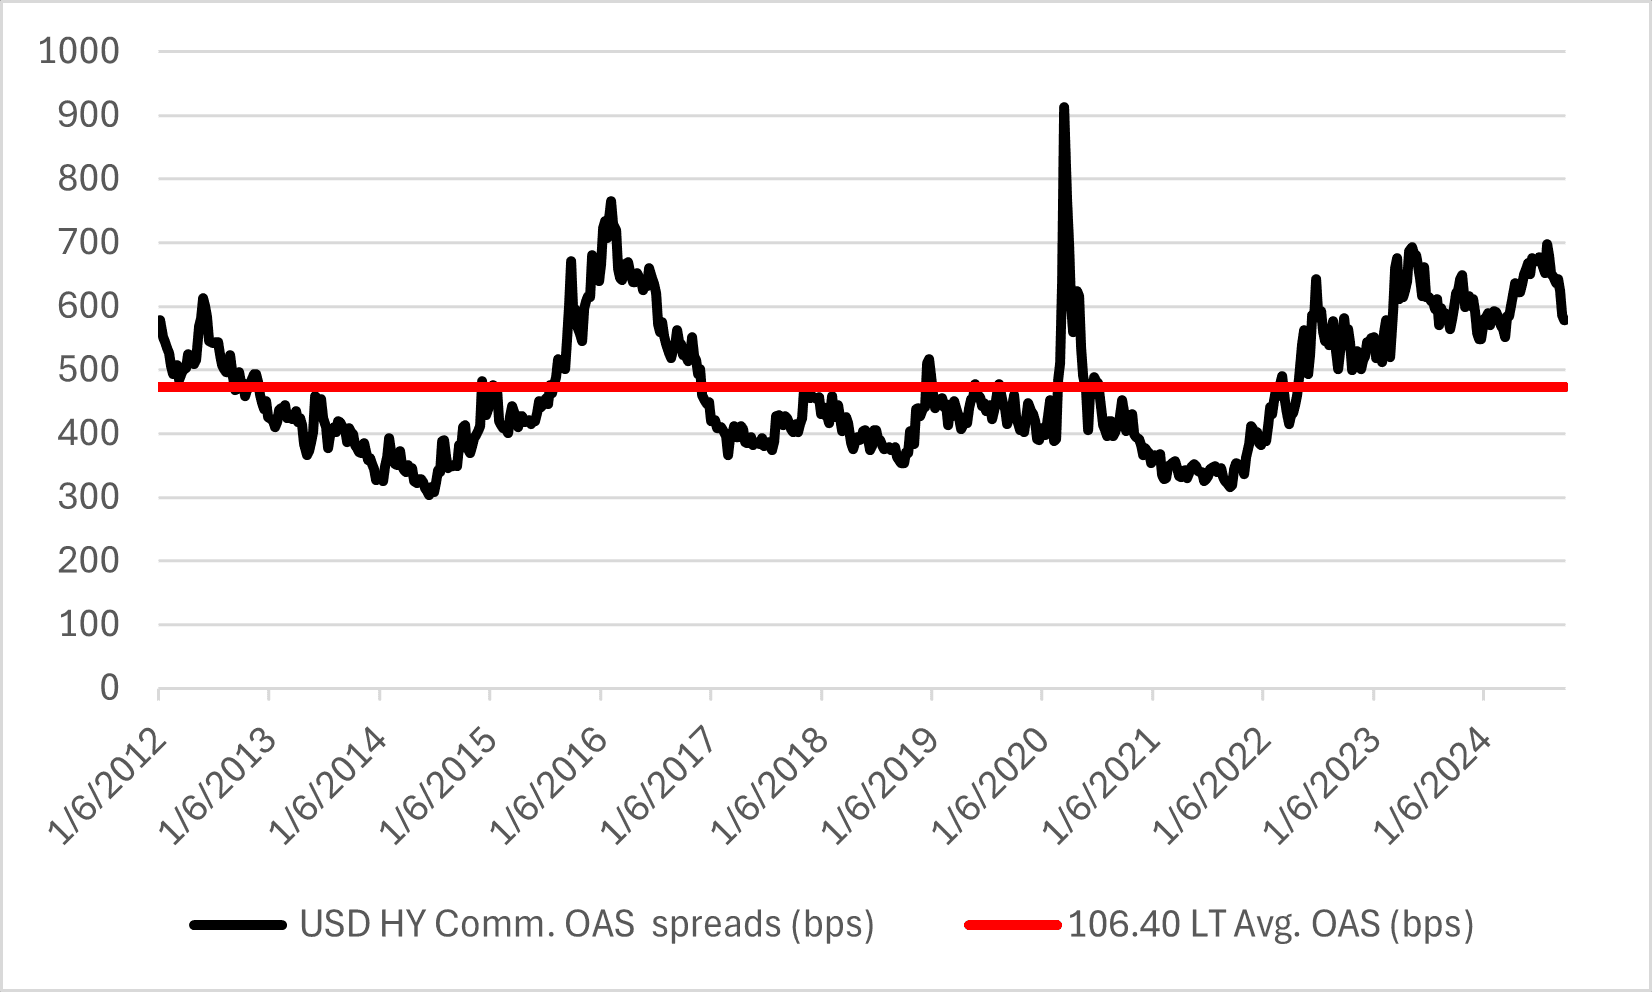
Current Spread at 578.49 bps trades 106.40 bps over its historical average with its all-time low spread being 319 bps in Sep 2021. Such a variance is largely due to the number of distressed securities in this sector.
Conclusion: Investors would do well by adding bonds from the above sector in their portfolios with a caveat that such additions should only be post a thorough fundamental analysis of the issuer. Suggest sticking to BB names in the sector.
Chapter 3- US EM Relative Value
Scanning through the 11 sectors that make up the universe led us to believe that all of them are trading in similar fashion below its long-term average. Such a phenomenon shifts the focus to bottom-up credit selection as opposed to top-down approach of finding relative value in sectors.
All investments carry risk, for more important information please read this disclaimer.


